
2024年9月試験 実技 問16
法令基準日 2024-04-01
問題
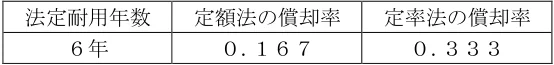
雑貨店を営む個人事業主の池谷さんは、2023年7月に自動車(新車)を購入し、その日から事業の用に供している。購入した自動車に関する内容等が下記<資料>のとおりである場合、下記<資料>に基づく池谷さんの2024年分の所得税における事業所得の金額の計算上、必要経費に算入すべき減価償却費の金額として、正しいものはどれか。なお、池谷さんは個人事業の開業年分(2022年)において、車両の減価償却方法として定率法を選定しており、この自動車を2024年12月末まで引き続き事業の用に供するものとする。また、償却保証額は考慮しないものとし、計算過程および計算結果において、円未満の端数が生じる場合は切り上げること。 <資料> [自動車に関する内容] 取得年月 法定耐用年数 取得価額 事業専用割合 2023年7月 6年 4,200,000円 100% [耐用年数表(抜粋)] 法定耐用年数 定額法の償却率 定率法の償却率 6年 0.167 0.333
図表・資料の画像を見る
図表と資料の配置を原典の該当部分から表示しています。問題文は上のテキストで読めます。

公式模範解答を見る
3. 1,165,734円
表記・単位・複数空欄の組合せは公式模範解答に合わせています。配点は協会非公表です。
解き方・判断の根拠
The question's conditions are: declining-balance method (定率法, rate 0.333), acquisition cost 4,200,000円, 100% business use, placed in business use in July 2023, used for the whole of 2024, and the depreciation guarantee amount is ignored. Round up any fraction below 1円 at each step. ① 2023 depreciation (prorated by month): July to December is 6 months. 4,200,000円 × 0.333 × 6/12 = 699,300円. ② Unamortized balance at end of 2023: 4,200,000円 − 699,300円 = 3,500,700円. ③ 2024 depreciation (in use all year, so 12 months): 3,500,700円 × 0.333 = 1,165,733.1円. Rounding up gives 1,165,734円. Business use is 100%, so the whole amount is a necessary expense. Because the question says to ignore the guarantee amount, there is no need to check against it or switch to the revised depreciation rate. The official answer is 3.
各選択肢の理由
1.Wrong. 4,200,000円 × 0.167 = 701,400円 is one full year of straight-line depreciation (定額法). The question says the declining-balance method (定率法) was chosen.
2.Wrong. This treats 2023 as a full 12 months: 4,200,000円 × 0.333 = 1,398,600円, then takes the remaining 2,801,400円 × 0.333 = 932,866.2円 and rounds up to 932,867円. The 2023 amount should have been prorated for 6 months (6/12).
3.Correct. 2023 prorated for 6 months: 699,300円. Unamortized balance at end of 2023: 3,500,700円. Multiplied by 0.333 = 1,165,733.1円, rounded up to 1,165,734円.
4.Wrong. 4,200,000円 × 0.333 = 1,398,600円 is the acquisition cost times the rate for a full 12 months. It does not deduct the 2023 depreciation (699,300円). It is not the same as the actual 2023 depreciation, which was 699,300円 after proration.
出典:日本FP協会 2級ファイナンシャル・プランニング技能検定 実技試験(資産設計提案業務)2024年9月試験。改行・空白を整え、図表がある設問では原典の該当箇所を画像で併記。